2026-10-16 ·
Insurance Claim Steps for Encino Fire Damage
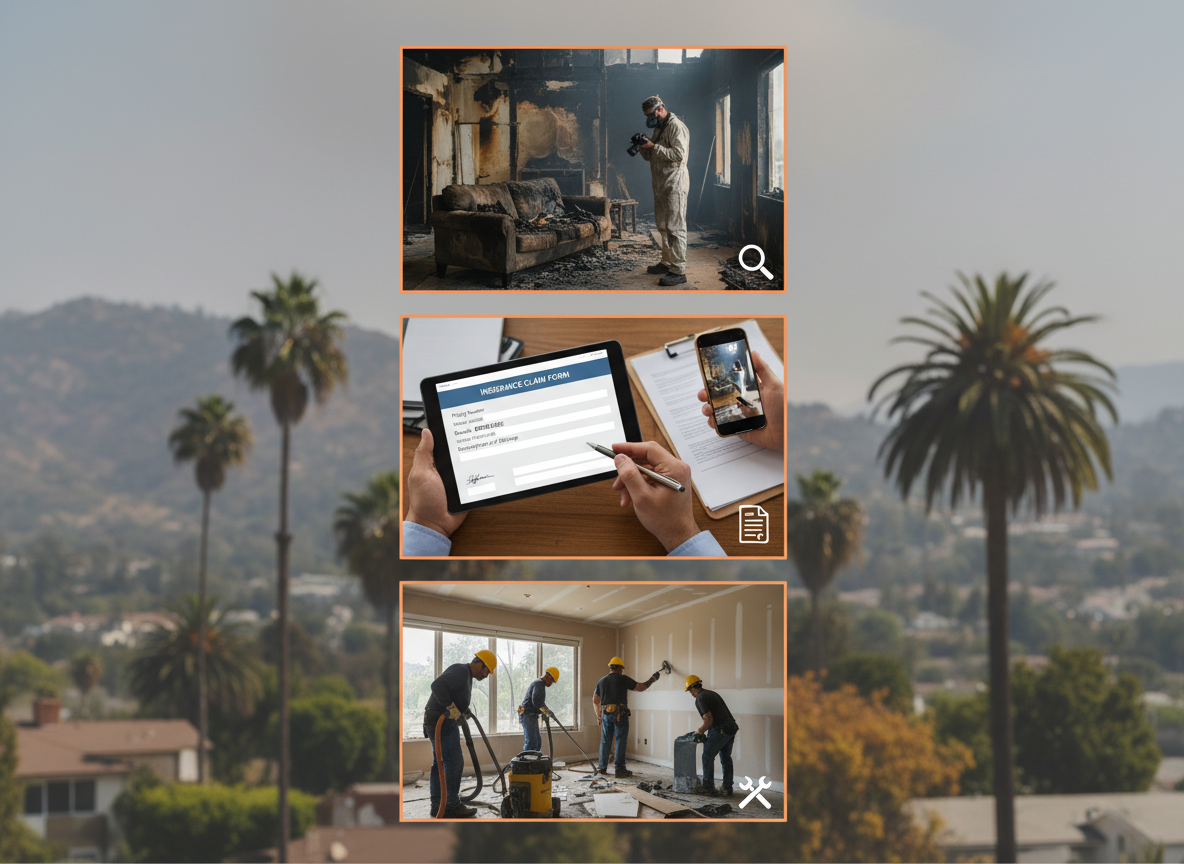
Filing an insurance claim for fire damage in Encino starts with notifying your carrier within 24 to 48 hours, documenting every affected room with photos and videos, and requesting an on-site inspection before any cleanup begins. Homes in Lake Encino and South Encino often feature mid-century construction with wood framing and older electrical systems that complicate loss assessment after a blaze. The hot-summer Mediterranean climate brings low humidity and Santa Ana winds that can spread embers quickly across properties near Encino Park and Los Encinos State Historic Park, leaving ash layers that insurers must evaluate separately from structural loss. Crews based at 16133 Ventura Blvd respond 24/7 to secure scenes and prevent further issues from shifting winds.
Notifying Your Insurer and Securing the Property
Contact your insurance company immediately after any fire in Encino, even if the damage appears limited to one room. Provide the policy number, date and time of the incident, and a preliminary description of affected areas such as kitchens or attics common in South Encino residences. Request emergency board-up and tarping to protect against the region's occasional winter rains that can worsen water intrusion into fire-weakened roofs. Keep a written log of every conversation, including adjuster names and reference numbers. This early step prevents disputes later when seasonal dry conditions accelerate soot settling throughout the structure.
Documenting Damage Specific to Encino Housing
Create a room-by-room inventory with dated photos, videos, and written notes before any restoration begins. Encino properties near Ventura Boulevard frequently contain built-in cabinetry and hardwood floors from the 1950s and 1960s that require specialized evaluation for hidden char. Note smoke migration paths through HVAC systems, a frequent issue in Lake Encino homes with shared ductwork. Include receipts for any temporary living expenses incurred while repairs proceed. Cross-reference findings with a professional assessment to align with carrier requirements before moving to the next phase.
Working with Adjusters and Scope Approval
Schedule the adjuster visit promptly and walk through every impacted area together, pointing out details such as soot on Los Encinos State Historic Park-adjacent properties where terrain can affect access. Request a written scope of work that lists line items for demolition, cleaning, and reconstruction rather than accepting verbal summaries. In nearby Sherman Oaks and Tarzana, similar claims have shown that initial offers often omit attic insulation replacement or odor treatment in older plaster walls. Review the estimate line by line and submit supplemental requests with supporting photos within the required window. This process ensures coverage reflects actual conditions found in Encino's varied housing stock.
Coordinating Restoration and Final Payment
Once the scope receives approval, schedule work through certified local teams that understand Los Angeles County permitting for structural repairs after fire. Track all invoices and progress photos to submit for reimbursement of additional living expenses or code upgrades required in Encino. Understanding fire restoration costs in Encino helps set realistic expectations for line items like drywall replacement and HVAC cleaning. After completion, obtain a final walkthrough and release of claim documentation before signing off. Structural repair after fire teams familiar with the area can address hidden damage uncovered during demolition in Woodland Hills border homes.
Avoiding Delays Common in Regional Claims
Submit all requested documentation within stated deadlines and follow up in writing if responses lag. Hot, dry periods in Encino can extend drying times for water used during suppression, requiring moisture mapping that insurers sometimes overlook. Maintain copies of every email and form submitted. When disputes arise over coverage for contents versus structure, reference the original policy declarations page. Consistent communication with your carrier and restoration partner keeps the claim moving toward settlement without unnecessary extensions.